The 12th edition of what has become “Keay’s Insolvency” has just been issued.
I’d like to briefly explain the history of the text which provides some perspective on the development of insolvency law and practice itself.
It was the first book on insolvency law in Australia, that is, covering both personal and corporate insolvency.
Before Keay, we had standard texts on bankruptcy – Lewis and McDonald Henry & Meek – and winding up – McPherson – but insolvency was not seen as a collected discipline. That unfortunately continues today, to an extent, but it may have been the result of those early days of the constitutional inability of the Commonwealth to legislate for a Companies Act at federation. Significantly, the Companies Bill 1908 had lined up an Official Receiver role. Instead corporate insolvency developed separately in the state jurisdictions, and in private firms alone.
The fact that the book pulled the two bodies of insolvency law together was significant. It’s still trying.
First and following editions
The book first appeared in 1993 five years after the 1988 Harmer Report and at a time when significant insolvency reforms were pending but old corporate and bankruptcy law still applied.
The second edition came out only a year later, in 1994, following the corporate reforms under the Corporate Law Reform Act 1992, Part 5.3A voluntary administration in particular.
4th edition and following
Professor Andrew Keay enlisted me to assist him to write the 4th edition in 2002 which I was very pleased to do. When the 5th edition came around and after I had started what I thought was my component of it Andrew advised me that he was moving to the UK. That was quite understandable and I produced the 5th and then the 6th edition, in 2008, following.
The law reform and practice changes recommended by the Harmer Report had been implemented and changes were also introduced in bankruptcy in 1996, s 139ZQ notices being one, which corporate insolvency adopted 25 years later.
However the request by Harmer that there be an alignment of personal and corporate provisions did not occur, not unusual from a siloed public sector, and even more so in the private sector. ASIC and AFSA continued on their separate ways. This was evident from a 2010 Senate inquiry that was critical of ASIC and recommended its role be taken over by AFSA. It also highlighted the poor state of corporate insolvency law in comparison with bankruptcy. That ultimately led to the harmonisation changes in the Insolvency Law Reform Act 2016.
As to alignment of the laws, my contribution was to make a plaintive call in a 2009 law reform article for bankruptcy to at least be transferred away from A-Gs to Treasury and I’m pleased to say that occurred – in 2025.
The 7th and following
Meanwhile I had thought of calling in someone to assist and Jason Harris joined me on the 7th edition, issued in 2011. Jason and I had similar views not only about the law itself but how it actually operated in practice. Our thoughts were contained in ch 21, the appraisal chapter, as a foil to the textual explanations in the main chapters, which became chapter 1 in following editions.
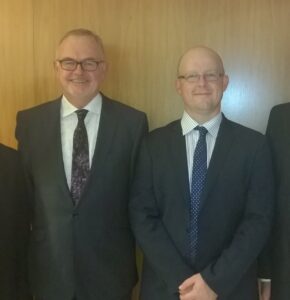
The authors, at the launch of the 8th
One example is the pursuit of preference claims which according to the theory are added to the estate to be shared by all creditors. That this does not occur is apparent. Similarly with claims about insolvent trading.
Various other deficiencies or uncertainties in the law are discussed throughout. We all should think critically about the law even while applying it. Nevertheless the text goes on to explain the law and practice as it is but it does make reference to its sometimes detachment from reality.
A restructure of Chapter 5
From a more advanced level we started to examine how the system was funded and came to the conclusion that it was “broke” that is monies remaining in its insolvent estates or recovered were simply not enough to maintain the system. We noted that a very large number of corporate insolvencies – by a factor of 5 – were simply deregistered by default with no liquidator scrutiny. With no Official Receiver role, the government simply accepted this.
At the same time liquidators were and are spending funds, if any, poring over dead businesses to report on misconduct often long after it had occurred. Chapter 5 should have been restructured long ago, under Part 5.3A.
The inherent limited funds and the significant public interest tasks, and costs, imposed on practitioners prompted us to say that there was a need for a greater role of the state in insolvency. Paul Heath’s “Insolvency Law Reform: The Role of the State” (1999) NZLRev 569 was an influence; and see our ‘Rebuilding the structure of the Australian insolvency system’ (2022) 22(1&2) INSLB 14.
PJC Report of 2023, and pending PC report of 2027
These views from chapter 1 of Keay were relayed in our submissions to the PJC on Corporate Insolvency, and many found their way into the 2023 Report, and recommendations. They were reviewed and provided in our submissions to the Productivity Commission inquiry of 2026.
Don’t forget the debtor
Meanwhile, the business market that insolvency purports to address was not standing still even if insolvency was. Insolvency assumes the debtor is either an individual or a company. Most small businesses do not operate in that separate way. The rather clunky insolvency process at present is the subject of study, since 2025, by myself and Dr Amanda Bull of QUT, and our submission to the Productivity Commission. That issue is also now raised in Keay.
Small corporates
Given the blended nature of debts in SMEs, we leave for the corporate lawyers a US comment as to whether
“the much-praised corporate form may be failing a growing number of entrepreneurs. Once heralded for its ability to shield owners from personal liability, corporate form may be meaningless [where] the debts are all personal debts”.
Competition
The other new issue raised and not raised elsewhere in Australia is what might be said to be the tension between insolvent restructuring and competition policy.
As former federal court judge Dr Arthur Emmett has asked – “why it would be in the interests of the business community generally to preserve inefficient enterprises?” which in economics terms should properly exit the market, thereby ensuring the business dynamism required for a healthy economy. A restructured debt-forgiven business comes back into the market with a significant competitive advantage.
The lawyers’ and policy answer of the need to protect employees, value, customers and so on may not be substantiated by the economic data.
In any event the answer to that is not definitive but while there is some debate in the UK and EU about this there is none here, save now for Keay’s Insolvency.
Corporate restructuring
Our insightful coverage of the practice of corporate restructuring continues, Jason necessarily being the main author. But we each reviewed and contributed to each other’s work.
Other features
We have retained the traditional structure. Future editions might see otherwise – for example writing a book from the context of the debtor, novel I know.
We have given many cross references between bankruptcy and corporate provisions. We have necessarily drawn on extensive case law and academic literature. Any omissions of relevant literature need not suggest they were not of influence; likewise if any judges are disappointed their decisions were not cited. Maybe next time.
We did try to limit the word count, but at just under 500,000 it is a bit below War and Peace, but both are far fewer than Murrays Legal.
Thanks
One final but important comment is to express my appreciation and thanks to my colleague and friend Jason Harris with whom I have had a long professional and personal relationship, extending, thankfully, well beyond insolvency law. We have presented together at the Hague and San Diego, before eminent fellows of the Academy of Law, fellow academics, parliamentary committees, and most recently in submissions to the PC.
Probably discussing safe harbour, in Barcelona
Keay has provided a convenient collection of our joint knowledge and expertise. We mostly agree, safe harbour being an exception 🙂
Thanks from both of us to Michelle Gavri of Thomson Reuters who probably has not had such time compliant authors as us two before, and her predecessors on earlier editions.
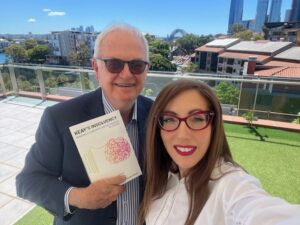
At Thomson Reuters, Sydney Harbour Bridge in the distance
Michelle suggested the cover …
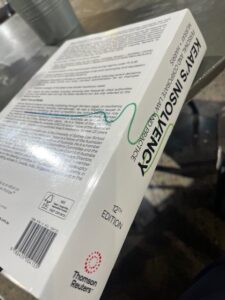
though she didn’t show me the back squiggle, right through my CV (which looks great!)
Why have we kept the name Keay in the title? It has a certain ring to it – “has anyone borrowed my Keays?” or from a judge, “but what does Keay say on this point?”, and there is precedent – Cheshire & Fifoot, McPherson, Dart, McDonald Henry, and others.
And it remains in due deference to Professor Andrew Keay for writing the first Australian text book on insolvency.
And thanks to Andrew for that out-of-the-blue email I received in 2001 inviting me to co-write with him.
