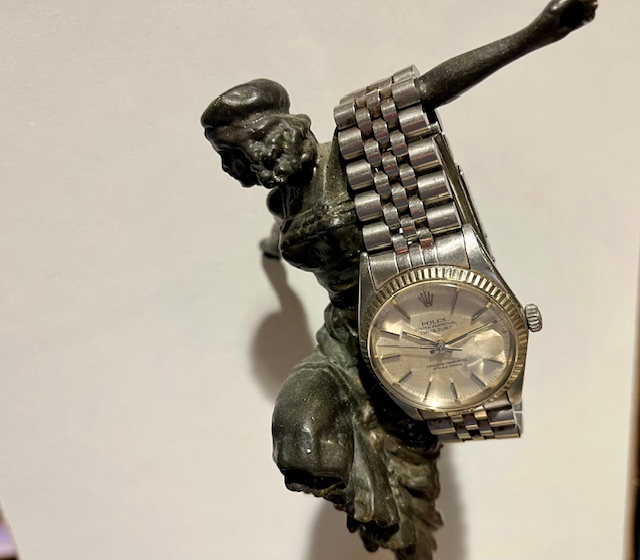
I have not updated my 2008 article on sentimental items of property in insolvency, including to check whether Rolex watches are still thrown on to the table at creditors’ meetings; or whether company funds are still used to purchase engagement rings for the director’s intended.
Sentiment in insolvency — (2008) 9(2) INSLB 29
Rolex watches
But by way of brief review, I do note that Rolex watches continue to feature as items of divisible property sought by trustees, in one case elevated to being termed ‘the Rolex objection’ [to discharge].[1]
In another case[2] despite the bankrupt denying having a Rolex Yacht-Master II watch, saying
‘The watch is gone. It’s flown away, like a bird. Gone’,
the AAT was satisfied as to the validity of the trustee’s objection to discharge (s 149D(1)(ma)) that the bankrupt had intentionally failed to disclose the watch.
Nothing is forever
In another case, in the course of the bankrupt’s examination, she said that various items including a gold Rolex watch and a three stone diamond ring
“were gifts to her, and at the time each was gifted to her she believed it was hers and hers forever” [3]
Nothing is forever.
The Rolex thrown on the table
And as I reported, a composition for debts of $261 million was offered under Part X comprising $10,000 immediately plus his Rolex watch thrown in (valued at $5,000 in his statement of affairs) and land in Italy, plus some litigation claims.
“The meeting of creditors went for over 6 hours”.[4]
The legal concept of an absolute gift – well, it was done up in pretty paper and it had a birthday card
And it is not only Rolexes. The Judge in one case queried why he was determining the title of paintings bought at a local art show. The wife of the bankrupt said they were a gift to her for her birthday.
Well, said counsel for the trustee,
“what did he say to you and what did you say to him?
No, he just gave me a birthday gift like most people give each other birthday gifts. I gave him —
Well, normally one would say something like, “This is a gift” and some words? —
Well, it was done up in pretty paper and it had a birthday card that said, “Happy Birthday, darling”. I can find those, I just don’t have any receipts.”
The Judge held they were the wife’s not the bankrupt’s.[5]
The purported owner of the paintings was the bankrupt’s mother
Finally, this one involved not only a Rolex watch and paintings but also some Lladro figurines.
The bankrupt was observed to be wearing the Rolex when he excused himself to go to the toilet and when he returned the watch was not to be found.
The court held that the watch should nevertheless be handed over to the trustee; the Lladro was found to have not been the bankrupt’s property; and the ownership of the paintings was stood over to allow the purported owner, the bankrupt’s mother, to be joined.[6]
Thanks for reading this far
In other respects, my 2009 article probably remains relevant, and perhaps useful, or at least amusing. Sentiment in Insolvency (2008) 9(2) INSLB 19.
))))))))))))))))))))))))))))))))))))))))))))))))))
[1] Fitz-Gibbon, in the matter of Fitz-Gibbon v Inspector General in Bankruptcy [2000] FCA 1677
[2] Stolyar and Inspector-General in Bankruptcy [2021] AATA 3398
[3] Lamb (Trustee), in the matter of Ariss (Bankrupt) v Ariss [2006] FCA 582
[4] Murray, Michael — “Bankrupt Law” [1999] NewDirBkrpt 2; (1999) 8(1) New Directions in Bankruptcy 3
[5] Murray, Michael — “Bankrupt Law (Michael Murray)” [1998] NewDirBkrpt 13; (1998) 7(2) New Directions in Bankruptcy 3
[6] Murray, Michael — “Bankrupt Law” [1998] NewDirBkrpt 3; (1998) 7(1) New Directions in Bankruptcy 3.